Buying your business premises through your super
A plain English guide for families who run a business and rent their workplace, covering how it works, what it really costs and the questions to ask first.
By Natalie Hawkes, Mortgage Broker 7 November 2026 6 minute read
You might rent a workshop, office, shop or consulting rooms and wonder whether your super could buy the building. For some business owners, a self-managed super fund (SMSF) can do exactly that, provided the property and arrangement meet the rules.1,2
Your business stays the tenant
An SMSF is a super fund that its members manage themselves. Buying through the fund means the property belongs to the super fund structure. It is not a building you own personally and can use however you like.
Your business continues paying rent, but the landlord becomes your SMSF. The rent goes into the fund and helps it meet loan repayments and expenses. Any money left stays in super for retirement. You cannot simply take it out to pay household bills.1,3
Why consider it
It may give your business more certainty about its location and allow your retirement savings to own an income-producing property. But the purchase still needs to make sense as an investment. A familiar building is not automatically a good buy, and property values can fall.
How the arrangement works
Where the property qualifies as business real property, your SMSF can generally lease it to your own business on commercial terms. This usually means land or buildings used wholly and exclusively in a business. Actual use matters; a commercial address or zoning alone is not enough. Mixed private use needs specialist advice.2
The business needs a properly documented, enforceable lease, evidence of market rent and payments made on time. Being both tenant and fund trustee does not let you charge a token rent, inflate the rent or informally stop paying.1,2,3
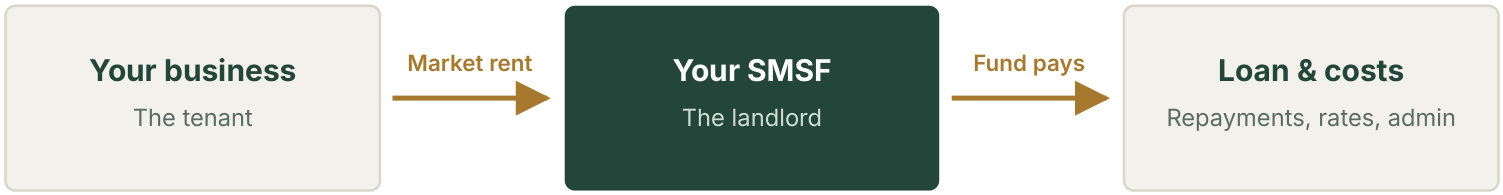
Any surplus stays in super for retirement. It cannot be withdrawn for household bills.
Sarah and Mark buy their workshop
Fictional example only. Figures are assumptions, not a client result, property valuation or loan offer.
Sarah and Mark run a cabinetmaking business from a rented workshop. Their landlord is willing to sell for $800,000. After getting advice, they decide their SMSF can buy it and lease it to the business for an independently supported market rent of $52,000 a year, excluding GST and agreed outgoings.
| THE PURCHASE | ILLUSTRATIVE AMOUNT |
|---|---|
| SMSF cash before purchase | $400,000 |
| Property price | $800,000 |
| SMSF deposit (35%) | $280,000 |
| SMSF loan at 65% of the price | $520,000 |
| Purchase and setup costs allowance | $50,000 |
| Cash left in the SMSF | $70,000 |
At an assumed 7.5% interest rate over 20 years, principal and interest repayments are about $4,189 a month, or $50,269 a year. Allow another $10,000 a year for property costs and fund administration after any tenant reimbursements.
The $52,000 rent therefore leaves a cash shortfall of about $8,269 a year before contributions. They need a workable plan to cover it. Contributions may help, subject to eligibility and caps, but cannot be assumed to continue forever.
At 9.5%, repayments would rise to about $58,165 a year and the shortfall to about $16,165. They also test a period without rent. Their remaining $70,000 is a buffer, not proof the investment is suitable.
Investment returns are excluded. Rates are hypothetical and no lender approval is implied.
Frequently asked questions
Q Can we buy the property we already rent?
Potentially, yes. The owner must agree to sell, the property must satisfy the relevant SMSF rules, and the price, lease and funding need to stack up. A shop, office or workshop may qualify, depending on how it is used.1,2
Q Does our business still have to pay rent?
Yes. Your business and SMSF are separate. The business pays commercial market rent under its lease, even though you manage the fund. Genuine rent is rental income to the fund, rather than a super contribution. Do not substitute extra rent for contributions.2,3
Q Can our SMSF borrow the money?
It may use a limited recourse borrowing arrangement, often called an LRBA. In simple terms, a separate holding trust holds legal title to the property for the SMSF while the loan is in place. The arrangement must meet strict rules and generally relate to a single asset. Your lawyer needs to check the structure before you sign.4
Q How much super do we need?
There is no single deposit or fund balance that works for everyone. Allow for the lender's deposit requirement, legal and advice costs, setup fees and cash reserves. The fund also needs money for ongoing expenses, repairs and future benefit payments. The case study is an example, not a minimum balance rule.1
Q Can we use the building privately?
Do not treat it as a family asset available for personal use. Living in it or adding private use can cause serious problems, especially with a related-party lease. Obtain advice before any change in use.2,3
Q What happens if our business closes or moves?
The SMSF still has its loan and expenses. It may need a new commercial tenant or may need to sell. A slowdown can affect both your household income and the rent funding your retirement investment. Plan for vacancy and a realistic exit.1
What to check before committing
The investment risk. Buying one building can put a large share of your retirement money into one asset. Think about diversification, cash reserves and how the fund would pay benefits if a member retires or dies. Your investment strategy must reflect the members' circumstances.1,3
The loan and ownership structure. SMSF lending involves specialist documents and can cost more than other lending. Limited recourse refers to the lender's rights against fund assets; it is not a promise that the investment or any personal guarantee is risk free. Ask your lawyer to explain every guarantee before signing.1,4
Future building work. Do not assume an SMSF property loan works like a home renovation loan. Changes to a property under an LRBA are restricted. Get advice before agreeing to extensions, redevelopment or a major fitout.1
A sensible order of steps
Check whether the strategy suits you
Speak with a financial adviser authorised to advise on SMSFs. Consider the effect on your retirement plan and any insurance before moving existing super.
Check the property and ownership structure
Your SMSF accountant and solicitor should review business use, the lease and the proposed ownership structure.
Check the finance
A broker can assess available SMSF lending options, likely repayments, lender requirements and the documents needed. Borrowing approval does not establish that the investment is suitable.
Get the structure right before signing
Confirm the correct purchaser, holding trust arrangements, contract conditions and setup sequence with your solicitor and lender. Fixing these later can be difficult and expensive.1,4
General information only. This article does not take account of your objectives, financial situation or needs and is not personal financial or legal advice. An SMSF and borrowing to invest are not suitable for everyone. Obtain advice from appropriately qualified professionals before establishing a fund, moving super or signing a contract. Rules and lender policies can change. Natalie Hawkes is Credit Representative 479789 of Australian Finance Group Ltd, Australian Credit Licence 389087.
SOURCES · CHECKED 7 NOVEMBER 2026
1. ASIC Moneysmart: SMSFs and property. moneysmart.gov.au/property-investment/smsfs-and-property
2. ATO: SMSFR 2009/1, business real property. ato.gov.au/law/view/document?docid=SMSFR/SMSFR20091
3. ATO: Running an SMSF, fast facts. smallbusiness.taxsuperandyou.gov.au/…/fast-facts
4. ATO: Borrowing. smallbusiness.taxsuperandyou.gov.au/…/borrowing